Author: Ajit Naskar

  • Aadhaar Update Guide 2026: What You Can Change Online and When a Centre Visit Is Needed

    Aadhaar Update Guide 2026: What You Can Change Online and When a Centre Visit Is Needed

    One-sentence summary: UIDAI’s online service currently supports address and document updates, while name, date of birth, gender, mobile number, email and biometric changes generally require an Aadhaar enrolment or update centre.

    Verified from: Unique Identification Authority of India FAQs, the Aadhaar Handbook 2026 and current enrolment-and-update regulations.

    What changed?

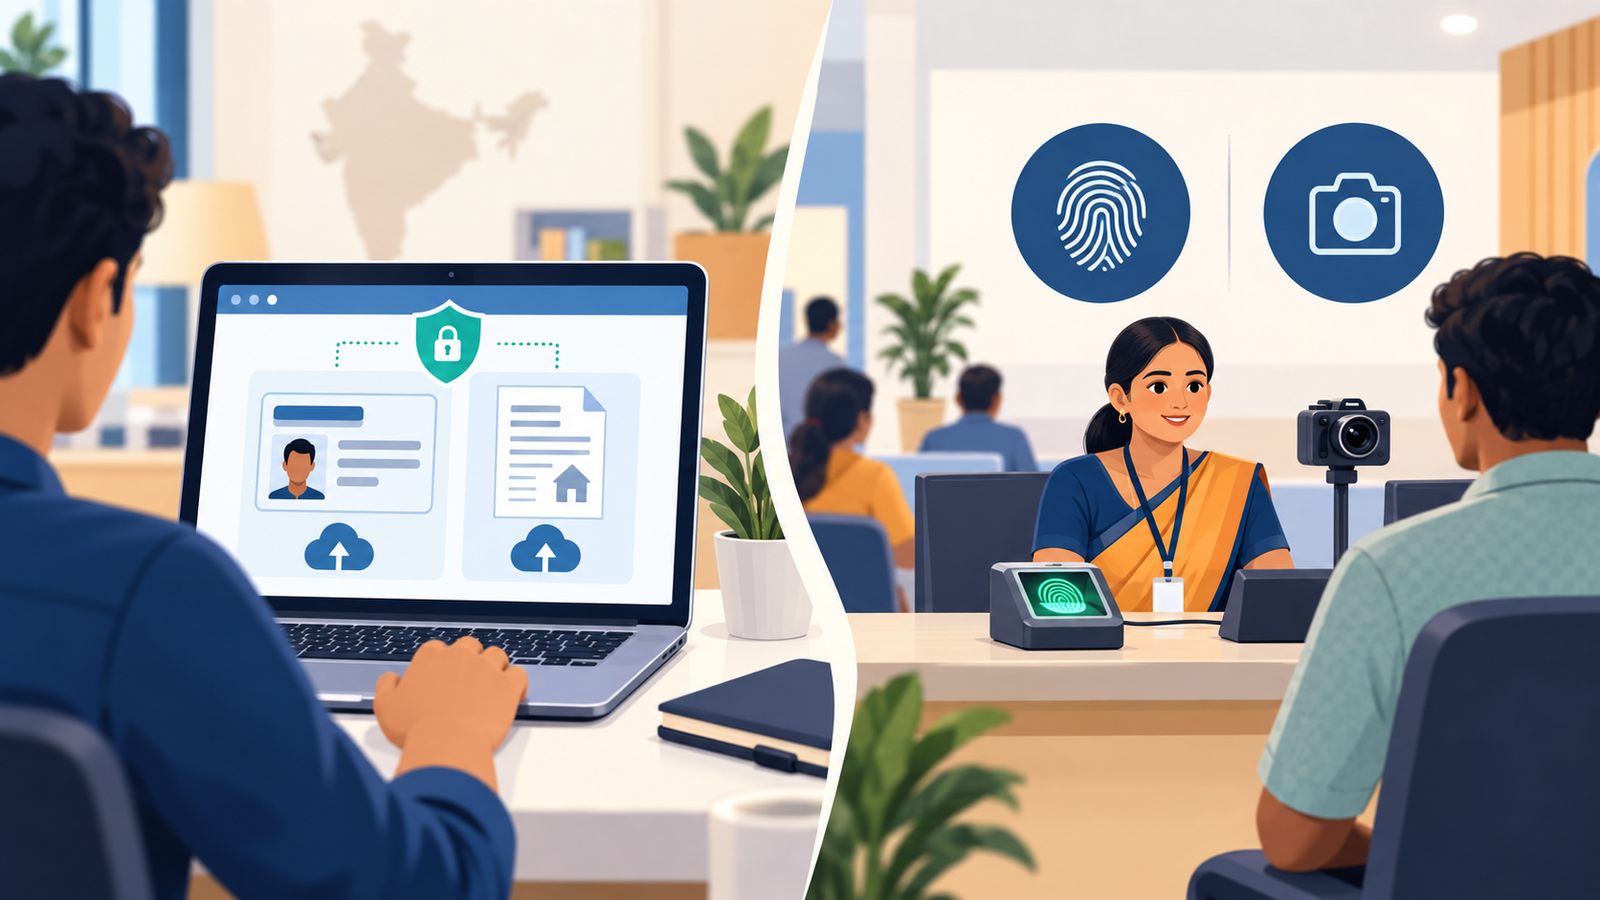
    This article explains the current division between UIDAI’s online update service and in-person services. It does not claim that every Aadhaar holder must update immediately. UIDAI says residents can use the online portal for address and document updates. Other demographic corrections and biometric changes require a centre visit.

    At an enrolment or update centre, available services can include changes to name, address, date of birth, gender, mobile number, email, proof-of-identity or proof-of-address documents, fingerprints, iris and photograph. Acceptance remains subject to UIDAI verification, supporting documents and applicable update limits.

    Who is affected?

    This guide is for Aadhaar holders who need to correct or refresh their identity, address, contact or biometric information. A registered mobile number is normally needed to authenticate online services. People without access to the registered mobile number, or those requesting a change not supported online, should use an authorised centre.

    Effective date

    The guidance was checked against UIDAI material available on September 9, 2026. UIDAI can change online capabilities, fees, documents and limits, so verify the service page again on the day you submit a request.

    What should the reader do?

    1. Identify the exact field that needs correction.
    2. For an address or document update, start only from myaadhaar.uidai.gov.in and review the current instructions.
    3. For name, date of birth, gender, mobile, email, photograph, fingerprints or iris, locate an authorised Aadhaar centre through UIDAI.
    4. Check the current list of accepted supporting documents and the fee before submitting.
    5. Keep the acknowledgement or service request number and use UIDAI’s official status service.
    6. Do not pay an unofficial agent or share an OTP with anyone.

    What does not change?

    Submitting a request does not guarantee approval. UIDAI verifies and validates the information before processing the change. Aadhaar remains an identity number; an update does not by itself establish eligibility for a separate government benefit or service.

    Example

    If a resident has moved home but their name and mobile number are correct, an online address update may be suitable if authentication and documents are available. If the same resident also needs a new photograph or mobile number, those changes require an authorised centre. This example is illustrative and does not replace UIDAI’s document rules.

    Important deadline

    There is no universal deadline in this guide requiring every Aadhaar holder to change details on the same date. UIDAI recommends keeping identity and address documents current. If another service gives you a deadline that depends on Aadhaar information, verify that deadline with the authority running that service.

    Official-source links

    FAQ

    Can I change my Aadhaar photograph online?

    No. UIDAI says photograph, fingerprint and iris updates require a visit to an Aadhaar enrolment or update centre.

    Can I update my mobile number online?

    UIDAI’s online portal FAQ says the portal supports address and document updates. For a mobile-number change, use an authorised centre and check whether UIDAI’s official app offers a newer route before starting.

    Does an online submission guarantee approval?

    No. UIDAI states that submitted information is verified and validated before an update is processed.

    Publication and updated dates

    Prepared: September 9, 2026. Last verified: September 9, 2026.

    Correction history

    No corrections.

    CheckMatter India is an independent publication and is not affiliated with or operated by the Government of India.
  • Repo Rate vs Loan Interest Rate vs EMI: The Difference Explained

    Repo Rate vs Loan Interest Rate vs EMI: The Difference Explained

    One-sentence summary: The RBI policy repo rate can influence floating loan pricing, but your bank’s benchmark, reset schedule, spread and chosen repayment option determine when and how your EMI or loan tenure changes.

    Verified from: Reserve Bank of India directions and FAQs on floating-rate EMI-based personal loans.

    What changed?

    This is an explainer, not a report of a new repo-rate decision. RBI rules require regulated lenders to explain how a benchmark-rate reset can affect an EMI-based floating-rate personal loan. When rates reset, the impact may appear as a higher EMI, a longer repayment tenure, or a combination of both.

    The repo rate is the policy rate at which the Reserve Bank of India lends short-term funds to banks against eligible securities. A retail loan rate is the rate charged by the lender to the borrower. For many floating-rate retail and MSME bank loans, the loan rate is linked to an external benchmark, which may be the RBI repo rate, plus the lender’s spread. The loan contract determines the benchmark, spread and reset frequency.

    Who is affected?

    The RBI’s reset framework applies to existing and new equated-instalment-based personal loans issued by regulated entities covered by the directions, including banks and specified non-bank lenders. Home loans are included when they fall within the RBI definition of personal loans. Borrowers with fixed-rate loans are not affected by every movement in a floating benchmark during the fixed period.

    Effective date

    The RBI required lenders to extend the reset framework to existing and new eligible loans by December 31, 2023. The master directions were updated on October 1, 2025. Always check the latest RBI text and your lender’s current policy before acting.

    What should the reader do?

    1. Read the Key Facts Statement and loan agreement to identify the benchmark, current spread, annual percentage rate and reset frequency.
    2. Check the lender’s latest quarterly statement for principal and interest recovered, EMI amount, EMIs remaining and annualised rate.
    3. If the rate resets upward, ask for a written comparison of a higher EMI, longer tenure, a combination of both, switching terms where offered, and part or full prepayment.
    4. Check every charge before switching or prepaying. Applicable charges must be disclosed, but the amount depends on the lender and current rules.
    5. Do not assume that a repo-rate change will alter your EMI immediately. Confirm the next contractual reset date.

    What does not change?

    A change in the repo rate does not automatically produce the same percentage-point change in every borrower’s rate on the same day. Fixed-rate loans follow their agreed terms. Even for floating loans, the benchmark, spread, reset interval, remaining balance and lender implementation determine the result.

    Example

    Suppose two borrowers have similar outstanding balances. One loan resets every three months and the other has not yet reached its reset date. A benchmark change may affect the first loan earlier. One lender may keep the EMI similar and extend the tenure, while another may offer the borrower a choice to raise the EMI. This example is illustrative; it is not a quotation or calculation from the RBI.

    Important deadline

    There is no universal borrower deadline in this explainer. The practical date is the next reset date stated in your loan documents and any response deadline in a lender’s notice. Record that date and request options before accepting a revised repayment schedule.

    Official-source links

    FAQ

    Does a repo-rate cut guarantee an immediate EMI reduction?

    No. The effect depends on whether the loan is floating, which benchmark applies, the reset schedule, the spread and the lender’s implementation.

    Can a lender change the tenure instead of the EMI?

    For eligible floating-rate EMI loans, RBI’s framework provides options that may include increasing the EMI, extending the tenure, or combining both. The lender must also prevent negative amortisation.

    Can a borrower prepay?

    The framework provides for part or full prepayment during the remaining tenure, subject to the RBI’s applicable instructions on foreclosure charges and prepayment penalties.

    Publication and updated dates

    Prepared: September 9, 2026. Last verified: September 9, 2026.

    Correction history

    No corrections.

    This article provides general information, not personal financial advice. Verify your loan terms with your lender.